Do You Need Flood Insurance in Brandon and Rankin County?
Do you need flood insurance in Brandon, Mississippi?
Flood insurance is only required in Brandon if the home sits inside a FEMA high risk flood zone (any zone label starting with A or V) and you are using a federally backed or federally regulated mortgage. Everywhere else it is optional, which is exactly why so many Rankin County homeowners skip it. Nearly a third of national flood insurance claims filed between 2014 and 2024 came from properties outside those high risk zones. Budget roughly $700 to $3,000 a year depending on the property, and make the call early in your contract rather than the week of closing.
Here is the question I get about three sentences after a buyer walks into a house they love near the Pearl River, the Reservoir, or any of the low lying pockets scattered through Rankin County: "Do I have to buy flood insurance on this one?"
Fair question. It is also one of the few costs in a Central Mississippi purchase that can genuinely blindside you, because it does not show up in a standard payment estimate and your homeowners policy will not quietly pick it up. Flood damage from rising water is excluded from every standard homeowners policy in Mississippi. If water comes up out of the ground and into the house, that is a separate policy or it is out of your pocket.
Anyone who was here in February 2020 remembers why this matters. The Pearl crested near its third highest level on record and hundreds of homes in the area took water. A lot of those owners found out the hard way what their homeowners policy did and did not do.
So let's walk through it the way I walk clients through it.
How to find out if a Brandon home is really in a flood zone
Do not rely on the listing photo, the seller's memory, or the risk score on a listing website.
That last one changed recently and it caught a lot of buyers off guard. Zillow pulled climate and flood risk scores off its for sale listings in late 2025 after pushback from the industry, while Realtor.com still displays a flood score. So depending on which app you happen to be scrolling, the same house can look like two different risks. Neither number is the official determination anyway.
Here is the actual order of operations:
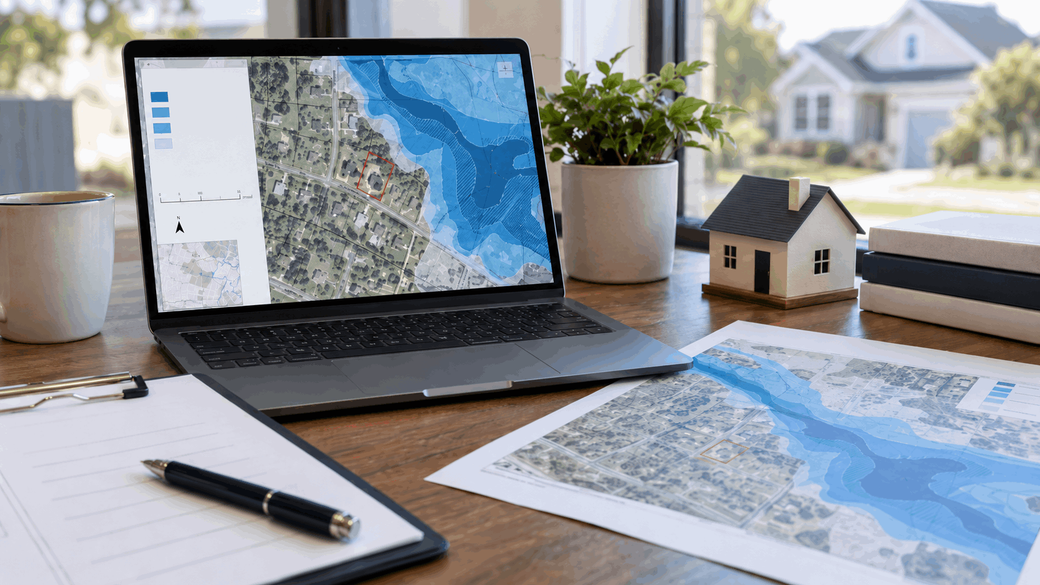
- Look the address up yourself on FEMA's Flood Map Service Center at msc.fema.gov. It is free, it takes about a minute, and it works by street address.
- Read the zone letter. Zones that start with A or V are Special Flood Hazard Areas, which is FEMA's term for high risk. Zones B, C, and X are the moderate to low risk designations.
- Ask your lender for the flood determination. Every lender orders one during underwriting. That determination, not a listing site, is what actually triggers a purchase requirement.
- If the home is mapped high risk but sits on high ground, ask about an elevation certificate. More on that in a second, because it can save you a few hundred dollars a year for as long as you own the house.
Worth knowing: a home inside a FEMA high risk zone has roughly a one in four chance of flooding at least once over the life of a 30 year mortgage. That is not a rounding error, and it is a bigger number than most buyers assume when they hear the phrase "100 year floodplain."
Now the part almost nobody mentions. If the structure sits above the base flood elevation even though the surrounding parcel is mapped high risk, a licensed surveyor can produce an elevation certificate, and you can submit it to FEMA as a Letter of Map Amendment request. FEMA does not charge a review fee for a LOMA. You pay the surveyor, typically a few hundred dollars. If FEMA agrees, the mandatory purchase requirement can come off the property entirely. I have seen that one document change whether a house was affordable for a buyer, so please do not write off a home in a mapped zone until someone has checked.
What flood insurance costs here, and what it actually covers
In Mississippi, expect a range of roughly $700 to $3,000 or more per year, with the statewide National Flood Insurance Program average landing somewhere near $1,430. A preferred risk policy on a home in an X zone often comes in near the bottom of that range, and a mapped high risk property with a low first floor lands near the top. Those are planning numbers, not quotes. Get a real quote on the specific address before you write the offer, not after.
Two things about coverage that surprise people:
- NFIP residential coverage caps at $250,000 for the building and $100,000 for contents. The average Brandon home value is running right around $290,000 right now, so that cap can leave a gap. Private flood carriers can write higher limits, and sometimes for less money, though not always. Compare both.
- Plenty is excluded. Below grade finished space is sharply limited, detached structures are not automatically covered, landscaping and decks generally are not covered, and a standard NFIP policy does not pay for temporary housing while you are displaced. Some private policies do. Vehicles fall under the comprehensive portion of your auto policy, not flood.
Flood is a separate line item from your regular coverage, and homeowners premiums in this market are their own conversation, one I broke down in detail in what homeowners insurance actually costs in Central Mississippi. Read the two together when you are building your real monthly number.
The 30 day waiting period, and the exception that saves your closing
A new NFIP policy normally takes 30 days to become effective. Buyers hear that on day 25 of a 35 day contract and understandably lose a little sleep.
Relax, then act. There is a long standing exception: when the policy is purchased in connection with making, increasing, extending, or renewing a loan, coverage takes effect at closing with no 30 day wait. A purchase qualifies. What does not qualify is deciding to add flood coverage a year into ownership, or a current owner adding it because the forecast looks ugly. Those wait the full 30 days.
The practical move is simple. Ask for the flood determination in the first week you are under contract, right alongside scheduling your inspection, so you have time to shop the policy instead of taking the first quote you can get on a Thursday afternoon before a Friday closing. If you want the full sequence of what happens between acceptance and the closing table, I mapped it out in what happens after your offer is accepted.
What the Pearl River flood control project could change
This is the piece that makes 2026 different from any year before it.
On February 26, 2026, the Army Corps of Engineers selected a plan for the long debated Pearl River flood control project, with the Rankin Hinds Pearl River Flood and Drainage Control District as the local sponsor. The selected plan involves levee work, widening and lowering sections of the river, elevating some structures, and voluntary buyouts. Estimates put the total cost between roughly $873 million and $918 million, with construction targeted to begin around the end of 2026 or early 2027 and expected to run about three years once it starts.
Why a buyer or seller should care: the district has said that FEMA will redraw the flood maps once the work is complete, and that many areas in Rankin County could come out of the 100 year floodplain as a result. For a home that comes off the high risk map, a federally backed mortgage would no longer require flood insurance at all.
Now the honest qualifier, because you deserve one. That is years away, it depends on funding and final engineering, and nobody should buy a house today on the assumption that a map gets redrawn tomorrow. Insurance you need in 2027 is insurance you need in 2027. But if you are weighing a home that is mapped high risk right now and you plan to be there ten or fifteen years, the long term trajectory is a legitimate part of the conversation, and so is the possibility that the flood control district's boundary expands and brings project related assessments with it for some property owners. Ask the question before you are under contract, not after.
If you are selling, flood history is a disclosure question
Mississippi's Property Condition Disclosure Statement asks about flooding and water intrusion history, and the standard is your actual knowledge. If the yard has taken water, if you have filed a claim, or if you carry a flood policy on the house, that belongs on the form. Leaving it off is how a seller ends up in a conversation with an attorney two years after closing. I covered the full disclosure duty in what you have to disclose when selling in Mississippi.
Two seller moves that actually help:
- Ask your insurance agent whether your NFIP policy can be assigned to the buyer. NFIP policies are generally transferable, and handing a buyer an existing policy can preserve an older rate. That is a real negotiating chip, not a technicality.
- If your home is mapped high risk but you believe the structure sits above base flood elevation, get the elevation certificate before you list. Removing that requirement for a buyer can be worth more than most of the cosmetic updates sellers agonize over.
Mississippi is an attorney closing state, so your closing attorney will handle the title and the paperwork at the table, but nobody at that table is going to solve an insurance problem for you on closing day. That part is on you and your agent to line up weeks earlier. If you want the full picture of who does what, here is how the closing attorney's role works in Mississippi.
Frequently Asked Questions
Is flood insurance required in Brandon, MS?
Only if the property is in a FEMA Special Flood Hazard Area, meaning a zone starting with A or V, and you are financing with a federally backed or federally regulated loan. Outside those zones it is optional, but it is still available and often inexpensive. Your lender's flood determination is the document that settles it.
How much does flood insurance cost in Central Mississippi?
Most Mississippi homeowners land somewhere between roughly $700 and $3,000 a year, with the statewide National Flood Insurance Program average near $1,430. Rates depend on elevation, distance to water, the year the home was built, and how much coverage you carry. Quote both an NFIP policy and at least one private carrier, because the cheaper option is not always the one you expect.
Does homeowners insurance cover flood damage in Mississippi?
No. Standard homeowners policies exclude damage from rising surface water, which is exactly what a river, a creek, or a flash flood produces. A burst pipe inside the house is usually covered, but water that comes in from outside is not. That is the entire reason a separate flood policy exists.
Can I get flood insurance removed if my house sits on high ground?
Sometimes, yes. Hire a licensed surveyor to prepare an elevation certificate, then submit it to FEMA as a Letter of Map Amendment request. FEMA charges no fee to review the request, and if the lowest floor is above the base flood elevation, the mandatory purchase requirement can be lifted for that property.
Do I have to wait 30 days for flood insurance when I am buying a house?
No. The standard 30 day waiting period does not apply when the policy is purchased in connection with a loan, so a policy bought for your closing takes effect at closing. The waiting period does apply if you add coverage later, which is why adding a policy when a storm is already in the forecast does not work.
Flood risk in Central Mississippi is not a yes or no question, it is a check the map, get the quote, and build it into the number question. Handle it in week one of your contract and it is a line item. Handle it in week five and it is a crisis.
If you want to know exactly what to expect at every step of buying a home here, whether you are touring next month or just starting to map out the plan, the Home Buyer Roadmap walks you through all of it, flood determination included. And if you are on the selling side and wondering what your home is worth before you sort out the insurance questions, you can get a quick starting number with the free Home Evaluation Tool.
Either way, I would rather you ask me early than find out at the closing table. That is what I am here for.
About April Smith
April Smith is a REALTOR® and Broker Associate with Southern Homes Real Estate, serving Brandon, Flowood, Pearl, Madison, Ridgeland and the surrounding Central Mississippi communities. She specializes in strategic marketing plans for every listing, drawing on her 20+ years of experience in media production and marketing prior to real estate. She works with first-time buyers, move-up buyers, and seniors, guiding each of them through every step of the process. Licensed since 2020 and holding the ABR, PSA, and C2EX designations, she ranks in the top 10% of the Central Mississippi MLS and is known for five-star client service across Google and Zillow. Her work is guided by her Christian faith and a commitment to serving every client with honesty, integrity, and the kind of attentive care that makes her clients feel personally guided through every step.
This article is general information about insurance and real estate process, not insurance, legal, or tax advice. Coverage, requirements, and flood map designations vary by property. Confirm the specifics for your address with a licensed insurance agent, your lender, and your closing attorney.
Recent Posts